A listener can encounter an unfamiliar artist in a playlist, explore their catalog, and return to a favorite track without buying a separate recording. That small change in the act of listening has enormous consequences. It changes the cost of musical curiosity and the way a recording earns money over time. Research on the adoption of streaming has documented both greater exploration and more varied listening.
The harder question is what follows that first encounter. Does someone remember the artist? Does discovery become sustained listening? How much of the money generated by those plays reaches the people who made the music? Answering those questions requires looking beyond a platform’s stream counter to its payment rules, recommendations, and relationship with the wider music business.
The Rise of Music Streaming
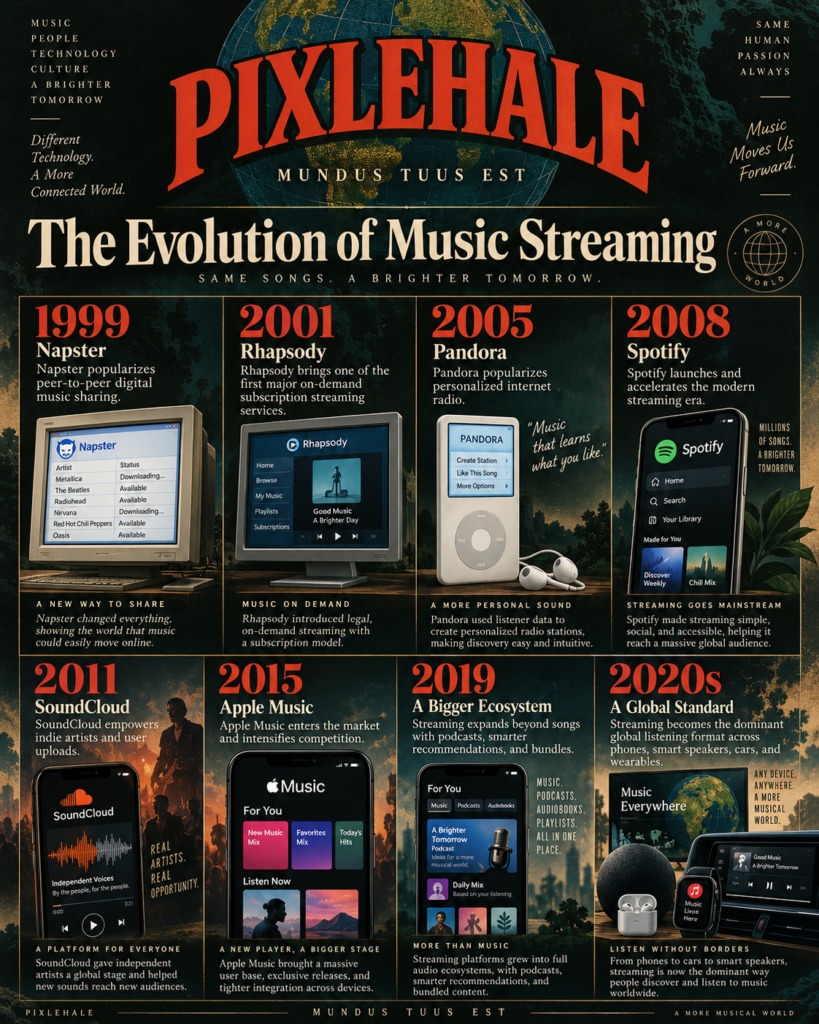
Spotify’s launch in six European countries in October 2008, followed by its mobile rollout in 2009, helped establish a model built around access to a catalog. Apple Music’s arrival in June 2015 brought another major technology company into subscription listening. These were milestones in a transition: listeners could increasingly pay for ongoing access to music, while advertising supported another route into streaming.
The scale is now substantial. IFPI, the trade organization representing record companies worldwide, reports that global recorded-music revenue reached $31.7 billion in 2025, up 6.4%. Streaming generated more than $22 billion and represented 69.6% of that total. Paid subscriptions alone supplied 52.4% of recorded-music revenue. These figures describe the recording business; they do not measure the entire music economy or musicians’ personal earnings.
The audience expanded alongside the revenue. IFPI reported 523 million users of paid subscription accounts at the end of 2021, compared with 837 million in its report covering 2025. Those are users of paid accounts, which should not be confused with the number of separately billed subscriptions.
The latest US figures show how unevenly formats are evolving. In the first half of 2026, streaming produced approximately $4.9 billion in wholesale recorded-music revenue, growing 4.7% from the same period in 2025. Downloads declined 12.7% to $121 million. Physical formats grew 25.9% to $731.5 million. Streaming dominates this market while other ways of paying for music persist.
For an individual recording, the commercial rhythm also changes. A purchase produces revenue at the point of sale; eligible streams can generate royalties through repeated listening over time. That gives a catalog an ongoing earning opportunity, although the value depends on how it is used and on the agreements governing it.
Impact on Artists and Creators
A sound recording and a song’s underlying composition sit within separate rights systems. The sound recording is the particular recorded performance; the composition is the musical work. Someone can perform a song without owning its composition, and one person can hold interests in both. Those distinctions help explain why a familiar recording can generate payments for several different parties.
On Spotify, recording payments generally pass through a label or distributor. Publishing payments move through publishers, collecting societies, and mechanical agencies, depending on the territory. Spotify describes allocating the relevant revenue through “streamshare”: the proportion of listening attributable to a rights holder. There is no universal fixed amount an artist receives for every stream. Listening patterns and contractual terms affect the result, and rights holders then pay creators according to their agreements.
This is why large payout announcements require careful reading. Spotify says it paid more than $11 billion to music rights holders in 2025, and that more than 81,000 artists’ catalogs generated at least $10,000 on the service. Its own explanation says these figures combine recording and publishing royalties generated by an artist’s full catalog. Spotify does not have visibility into everyone’s contracts or take-home income. Those are meaningful measures of economic activity, but they cannot establish how many musicians earned a living wage.
Independent evidence shows how opportunity and concentration can coexist. The UK Competition and Markets Authority’s 2022 study found that the top 0.4% of artists accounted for more than 60% of streams in 2020. It also found more distribution choices and improving terms in some new recording deals. The study did not conclude that competition problems primarily explained creators’ concerns and declined a further market investigation. These are historical UK findings, useful for understanding the tension rather than estimating today’s global income distribution.
Platform eligibility rules add another layer. Since April 2024, a recording on Spotify must reach at least 1,000 global streams in the preceding 12 months and meet an undisclosed minimum for unique listeners to enter its recording-royalty calculation. The rule excludes publishing royalties. A track earns recording royalties for streams in its first qualifying month, but earlier months are not paid retroactively. Spotify says the affected money is reallocated to eligible recordings.
Visibility can involve a financial trade-off, too. Spotify’s Discovery Mode is an optional promotional tool for eligible artists. Its current terms apply a 30% commission to recording royalties from selected songs in Discovery Mode contexts; other streams fall outside that commission. The offer creates a concrete business question: will additional discovery generate enough lasting value to justify the reduced return on those plays? The terms establish the cost, without establishing the answer for every participant.
Exposure and compensation therefore need separate scrutiny. Access to a worldwide platform can be valuable, while the money retained by a particular creator still depends on rights, contracts, eligible listening, and expenses. A stream total by itself cannot resolve that accounting. The same applies to creative success: a listener who discovers a song and a fan who follows an artist’s work represent different kinds of relationships, even if both begin with a play.
Changes in Listener Behavior
Streaming fits into a wider listening life. IFPI’s Engaging with Music 2023 surveyed more than 43,000 people aged 16–64 across 26 countries. Respondents used more than seven methods to engage with music on average, and 73% reported using licensed audio streaming. Its listening-time estimate, based on 18 core countries, was 20.7 hours per week. These are 2023 survey results, offering context rather than a measurement of current 2026 habits.
Research helps explain what happens when trying unfamiliar music becomes inexpensive. In a study published in Marketing Science, Hannes Datta, George Knox, and Bart Bronnenberg found that adopting Spotify increased the variety of artists, songs, and genres people heard. The effects persisted beyond the initial adoption period. Their analysis used listening histories from 2013–2015 and compared adopters with matched nonadopters. It was not a randomized experiment, and its relatively young, predominantly male sample limits how broadly the findings should be applied today.
Having a large catalog available also makes selection important. A listener may choose an album, build a playlist, follow an editor’s recommendations, or accept an automated queue. Each route presents music in a different context. The research question is consequently more specific than whether streaming broadens taste: which ways of using a service encourage exploration, and for whom?
A 2020 paper by Spotify-affiliated researchers illustrates that complexity. In the platform data they examined, most users’ self-directed listening was more diverse than their algorithmically programmed listening. The authors explicitly warned that this association did not establish that recommendations caused narrower tastes. People with narrower preferences might simply choose programmed listening more often. Their separate randomized recommendation test found personalized suggestions worked better than popularity-only suggestions on its short-term performance measure.
Placement nevertheless has consequences. Economists Luis Aguiar and Joel Waldfogel estimated that inclusion in Spotify’s Today’s Top Hits playlist produced approximately 260,000 additional worldwide daily streams in their historical analysis. Their study used 2016–2017 data and changes around playlist placement, among other methods. The estimate is evidence that platform promotion can affect exposure, rather than a promise of what a playlist slot delivers today.
These findings describe several processes operating together: access can support exploration, recommendation design can shape the next choice, and prominent placement can direct attention. They also leave room for listener agency. Choosing an unfamiliar album or following a friend’s recommendation remains a different act from letting a service continue a queue, even when both happen inside the same app.
Cultural Implications of Streaming
Music’s international circulation is visible in current listening data. Luminate reports that Spanish-language music accounted for 9.4% of US on-demand audio and video streams in the first half of 2026. It also reports that American artists retained more than two-thirds of US streams. Language and artist nationality are different measures, but together these findings show why international reach should not be confused with the disappearance of local preferences. Neither statistic, by itself, proves streaming caused the pattern.
Platform promotion can operate at the level of individual songs. Spotify’s Release Radar updates weekly and supplies music from artists a listener follows, has heard, or may like. Each listener receives at most one song per artist per week. That is a specific example of promotional space organized around tracks, even when an artist releases an album. It creates reasons to think carefully about which song introduces a larger work.
The album still has an economic presence. RIAA’s first-half 2026 figures put US vinyl revenue at approximately $544 million and CD revenue at $171 million, both higher than a year earlier. Those figures measure purchases, not whether people stream albums from beginning to end. They nevertheless show continued demand for music in physical form alongside streaming’s much larger business.
An artist’s older recordings also remain part of this competition for attention. The CMA noted that convenient access was helping older music find renewed audiences while increasing the catalog competing with new releases. For listeners, that creates opportunities to discover work they missed the first time. For emerging artists, it means releasing into a space that includes music from across generations.
The likely next phase, as an interpretation of this evidence, is a continuing struggle over the relationship between discovery and attachment. Services can make more music available, but the prominence given to a recording still depends on choices about curation, recommendations, and promotion. Artists can benefit from those systems while seeking relationships that survive a change in playlist placement. Listeners can use convenience to explore, collect, or spend more time with an artist’s wider work.
Several outcomes remain open. Recommendation systems could place greater emphasis on exploration. Commercial incentives could favor repeated engagement with familiar material. Physical releases and other forms of fan support could keep growing alongside streaming. These are possible directions, not measured forecasts, and the evidence does not justify declaring a single future for music culture.
Streaming has made a first listen easier to obtain. Whether that first listen becomes a lasting audience—and whether the people behind it can sustain their work—remains the more revealing measure of what the streaming era delivers.
Sources: Key data and findings in this article are drawn from IFPI, the Recording Industry Association of America, Luminate, the UK Competition and Markets Authority, Spotify, Apple, and The Mechanical Licensing Collective. Additional analysis draws on research published in Marketing Science and presented by Spotify Research and CEPR. Together, these sources inform the article’s examination of streaming revenues, artist compensation, listening habits, and music discovery. Company disclosures are attributed to their original sources, with reporting periods and research limitations noted throughout.